


Lumentum (LITE) develops optical and photonic products that move, route and sense data across cloud networks, telecom infrastructure and industrial systems. Lasers and optical components remain central to the business, with cloud modules and optical circuit switching becoming more important as AI clusters require higher bandwidth. That transition broadens Lumentum's exposure to AI infrastructure, though it also leaves the stock sensitive to hyperscaler spending, manufacturing yields and elevated valuation.
Its latest quarter showed that the transition is already changing the financial profile. Lumentum fiscal Q4 2026 revenue reached $1.006 billion, up 109.3% year over year, as components revenue rose 102.7% and systems revenue increased 122.6%. Non-GAAP gross margin reached 50.4%, supporting stronger earnings even as a one-time debt-extinguishment charge distorted GAAP net income.
The LITE stock forecast for 2026 now centers on two competing views:
- The AI optical scale case: 1.6T modules, optical circuit switches and in-rack laser products can expand revenue and margins as cloud customers move more data from copper to light.
- The execution and valuation case: capacity bottlenecks, customer timing or slower CPO adoption could flatten estimate revisions after a 153.86% year-to-date rally.
This guide breaks down the LITE stock forecast, 2026 price scenarios, key risks and analyst outlooks, drawing on Lumentum's August 11 fiscal Q4 2026 earnings release, annual filing and market data through September 10, plus how to trade LITE stock futures on BingX TradFi with USDT collateral.
Top 5 Things for Lumentum Investors to Know in September 2026
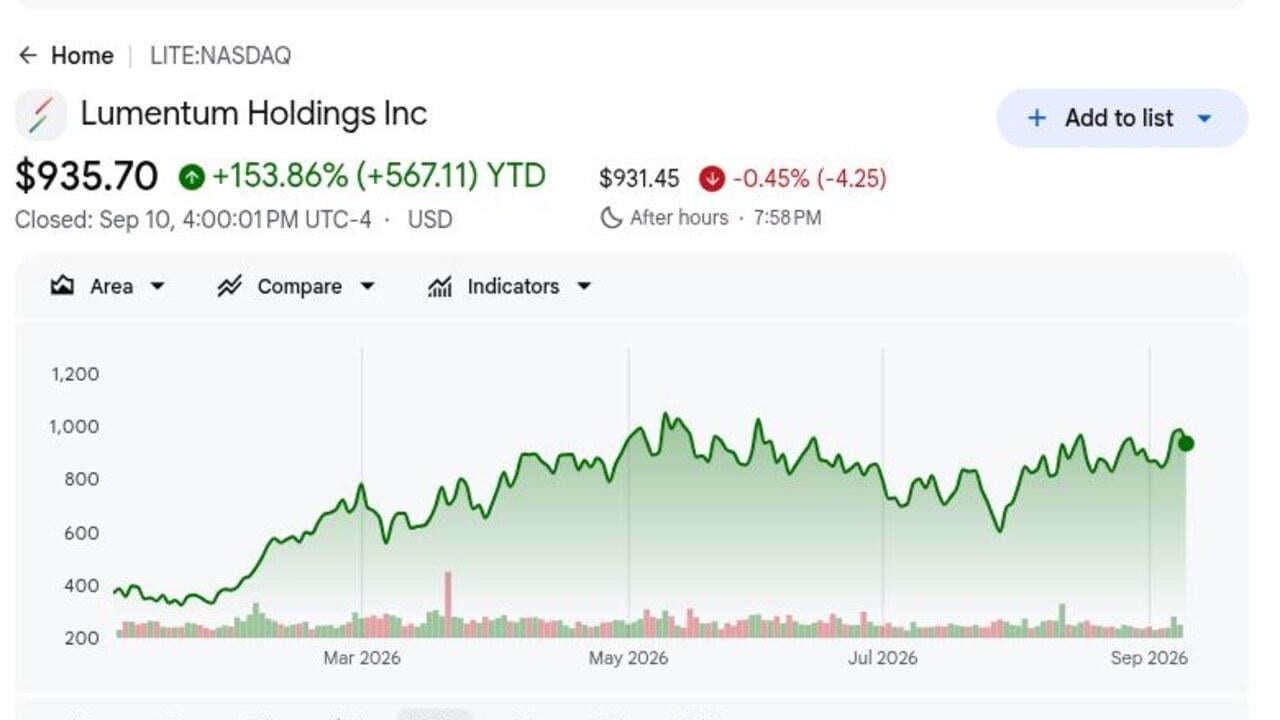
- LITE closed at $935.70 after gaining 153.86% YTD: The rally reflects strong AI-optics demand, though shares remained below the May 11 high of $1,053.09. That gap shows how quickly valuation can compress when investors question optical deployment timing.
- Fiscal Q4 revenue reached $1.006 billion, up 109.3%: Sales rose 24.5% sequentially from $808.4 million and beat consensus by about $51 million. The first billion-dollar quarter showed that cloud transceiver, laser and switching demand is translating into revenue.
- Non-GAAP gross margin expanded 1,260 basis points to 50.4%: Margin also rose 250 basis points sequentially and topped the roughly 48% expectation. Better mix and scale show that rising optical demand is converting into stronger profitability.
- The Q1 FY2027 revenue midpoint rose to $1.25 billion: Guidance of $1.225 billion to $1.275 billion implies about 24% sequential growth at the midpoint. Non-GAAP EPS guidance of $4.05 to $4.35 and operating margin of 39.5% to 40.5% point to further leverage.
- NVIDIA committed $2 billion to Lumentum's optical capacity: The agreement includes purchase commitments and future access to laser and networking products. The opportunity is significant, though new capacity still needs to qualify on schedule and convert into profitable shipments.
What Is Lumentum (LITE)?
Lumentum is a global photonics manufacturer whose lasers, modules and optical subsystems enable data transmission and sensing. Its components business supplies laser chips and optical building blocks, while its systems portfolio includes cloud modules and optical circuit switching products that route light through networks. Customers span cloud and internet companies, telecom equipment vendors, industrial manufacturers and sensing-device makers. Lumentum combines internal research and manufacturing with outside suppliers and contract manufacturers, making product yield, capacity and qualification central to its economics.
The long-term strategy increasingly targets AI optical and photonics infrastructure. Lumentum is advancing 1.6T cloud modules, optical circuit switches, external laser source modules, near-packaged optics and ultra-high-power lasers for co-packaged systems. NVIDIA's $2 billion investment adds a strategic customer and funding for U.S. capacity, while a supply agreement with AXT supports indium-phosphide inputs through 2031. These programs aim to extend Lumentum from links between racks into shorter optical connections inside AI systems.
Read More: Top AI Optical Stocks to Buy in 2026: Photonics, Optics, Fiber, and Data Center Interconnects
Lumentum (LITE) Q4 FY2026 Earnings Overview: Revenue, Margins and AI Optical Growth
Lumentum delivered $1.006 billion of revenue versus roughly $955 million expected, non-GAAP EPS of $3.23 versus about $2.80 expected and 50.4% non-GAAP gross margin versus roughly 48%. Components grew 102.7% to $649.4 million and systems rose 122.6% to $356.9 million. Q1 FY2027 revenue guidance reached $1.225 billion to $1.275 billion, though a $7.8 billion non-cash debt-extinguishment loss made GAAP net income a poor measure of operating performance.
Read More: Lumentum (LITE) Q4 FY2026 Earnings Overview: $3.23 Adjusted EPS Beat Drives a 13.63% Price Rally
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
Q4 FY2026 revenue |
About $955M consensus |
$1.006B |
Beat. About $51M above consensus; up 109.3% YoY. |
|
Non-GAAP diluted EPS |
About $2.80 |
$3.23 |
Beat. About $0.43 above consensus; up from $0.88. |
|
GAAP net loss |
— |
$7.162B loss |
Distorted. A $7.8B non-cash debt-extinguishment loss drove the result. |
|
Non-GAAP gross margin |
About 48.0% |
50.40% |
Beat. About 240 bps above consensus; up 1,260 bps YoY. |
|
Non-GAAP operating margin |
Q3 actual 32.2% |
36.60% |
Expanded. Up 440 bps sequentially. |
|
Components revenue |
Q4 FY2025 $320.4M |
$649.4M |
Accelerated. Up 102.7% YoY. |
|
Systems revenue |
Q4 FY2025 $160.3M |
$356.9M |
Accelerated. Up 122.6% YoY. |
|
Cash and short-term investments |
Q3 $3.172B |
$2.738B |
Lower. Down $433.9M sequentially. |
|
Q1 FY2027 revenue outlook |
About $1.10B |
$1.225B–$1.275B |
Above. Midpoint exceeded consensus by about $150M. |
|
Q1 non-GAAP operating margin |
— |
39.5%–40.5% |
Higher. Midpoint implies 340 bps of sequential expansion. |
|
Q1 non-GAAP EPS outlook |
About $3.35 |
$4.05–$4.35 |
Above. Midpoint exceeded consensus by about $0.85. |
- Revenue of $1.006 billion grew 109.3%: Sales more than doubled from $480.7 million and rose 24.5% sequentially, showing that multiple cloud-photonics programs are scaling together. The result also sets a much higher base for fiscal 2027.
- Non-GAAP EPS reached $3.23 versus about $2.80 expected: Earnings rose from $0.88 a year earlier as gross margin moved above 50%. The improvement shows that stronger volume and mix are translating into operating leverage.
- Components and systems grew 102.7% and 122.6%: Components generated $649.4 million and systems contributed $356.9 million. Growth across lasers, modules and switching products reduces dependence on one optical category.
- Non-GAAP operating margin expanded to 36.6%: Margin rose from 15.0% a year earlier and improved 440 basis points sequentially. That gives Lumentum more room to fund capacity and product development while growing profit.
- The $1.25 billion Q1 midpoint implies about 24% sequential growth: A 40.0% operating-margin midpoint and $4.20 EPS midpoint suggest the AI optical ramp is still accelerating. Both ranges were also materially above cited consensus.
Lumentum (LITE) 2026 Investment Outlook: $1,300 Bull Case vs. $700 Bear Case
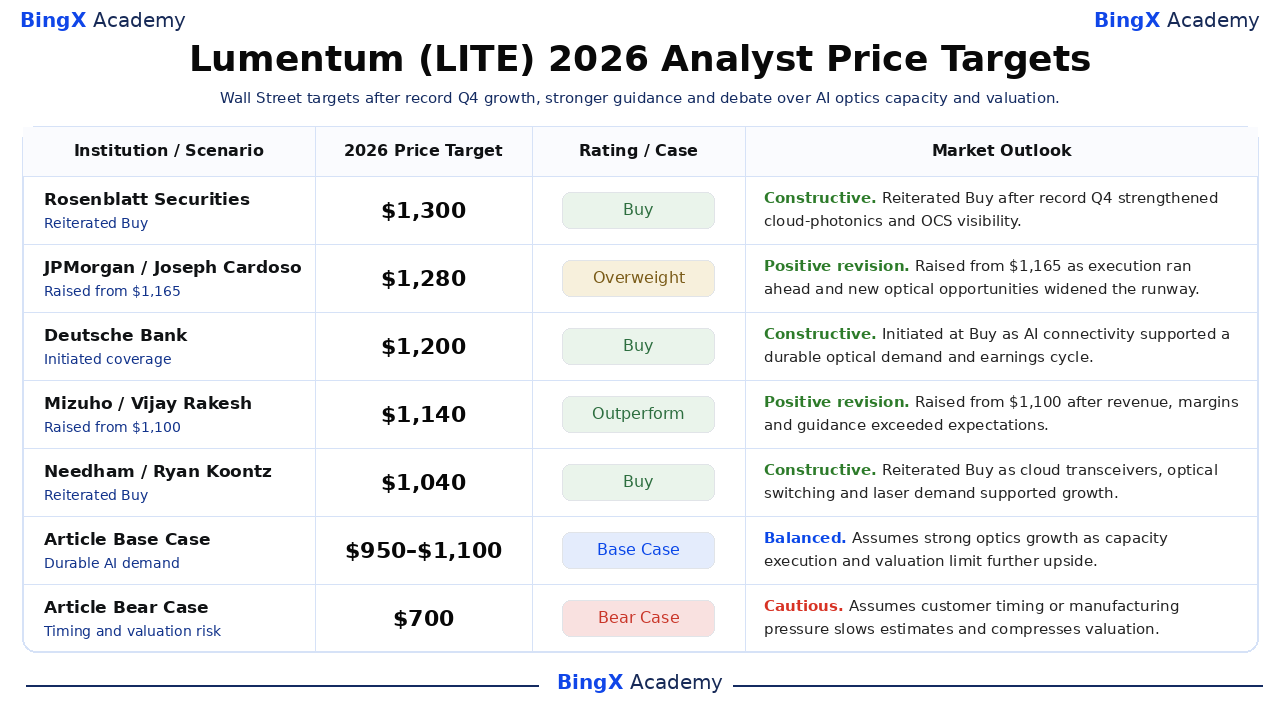
The 2026 outlook depends on how quickly 1.6T modules, OCS and emerging in-rack optical products convert from customer programs into shipments. The three ranges below are editorial scenarios rather than Wall Street targets.
The Bull Case: Strong AI Optics Demand Pushes LITE Toward $1,300
The Bull Case assumes cloud modules and optical circuit switches keep scaling as Lumentum adds 1.6T products and higher-power lasers. Q1 revenue reaches or exceeds the $1.275 billion guide ceiling, while non-GAAP operating margin stays near 40%.
A move toward $1,300 would require new manufacturing to qualify on schedule, NVIDIA commitments to convert into shipments and in-rack optical adoption to broaden. Continued estimate increases and gross margin at or above 50% would strengthen the case.
The Base Case: Steady AI Demand Keeps LITE Between $950 and $1,100
The Base Case assumes AI network investment remains strong and current products continue growing, though newer optical technologies scale unevenly. Revenue keeps rising from the $1.006 billion Q4 base, while capacity expenses limit further margin expansion.
Under this scenario, LITE could trade mainly between $950 and $1,100. Revenue near guidance, non-GAAP operating margin in the high 30s and stable customer schedules would support the range.
The Bear Case: Slower AI Spending Pulls LITE Toward $700
The Bear Case assumes hyperscalers delay deployments or manufacturing yields limit shipments as expectations remain high. Slower OCS or 1.6T adoption would leave new capacity underused and weaken earnings growth.
A move toward $700 would become more likely if guidance falls below the $1.225 billion Q1 floor, gross margin drops materially from 50.4% or analysts cut forward estimates. Slower growth would make the current valuation harder to sustain.
LITE Stock Price Forecasts for 2026 By Wall Street Analysts
Wall Street remained positive overall after fiscal Q4, though target dispersion reflects debate over how much AI optical growth is already priced in after the 153.86% YTD gain. The table separates five current analyst actions from the article's editorial scenarios and preserves each institution's rating context.
|
Institution / Analyst |
2026 Price Target |
Rating / Case |
Market Outlook |
|
Rosenblatt Securities / Mike Genovese |
$1,300 |
Buy |
Constructive. August 12: reiterated Buy after record Q4 strengthened cloud-photonics and OCS visibility. |
|
JPMorgan / Joseph Cardoso |
$1,280 |
Overweight |
Positive revision. August 12: raised from $1,165 as execution ran ahead and new optical opportunities widened the runway. |
|
Deutsche Bank / Gianmarco Conti |
$1,200 |
Buy |
Constructive. August 31: initiated coverage as AI connectivity supported a durable demand and earnings cycle. |
|
Mizuho / Vijay Rakesh |
$1,140 |
Outperform |
Positive revision. August 12: raised from $1,100 after revenue, margins and guidance exceeded expectations. |
|
Needham / Ryan Koontz |
$1,040 |
Buy |
Constructive. August 12: reiterated Buy as cloud modules, switching and laser demand supported growth. |
|
Article Base Case |
$950–$1,100 |
Base Case |
Balanced. Assumes strong optics growth as capacity execution and valuation limit further upside. |
|
Article Bear Case |
$700 |
Bear Case |
Cautious. Assumes customer timing or manufacturing pressure slows estimates and compresses valuation. |
How to Trade Lumentum (LITE) Stock on BingX
Trade Lumentum's AI-optics, margin and capacity outlook using BingX TradFi and BingX AI tools. Because LITE can react sharply to hyperscaler spending, product ramps and guidance, traders should define the catalyst and risk limits before entering a position.
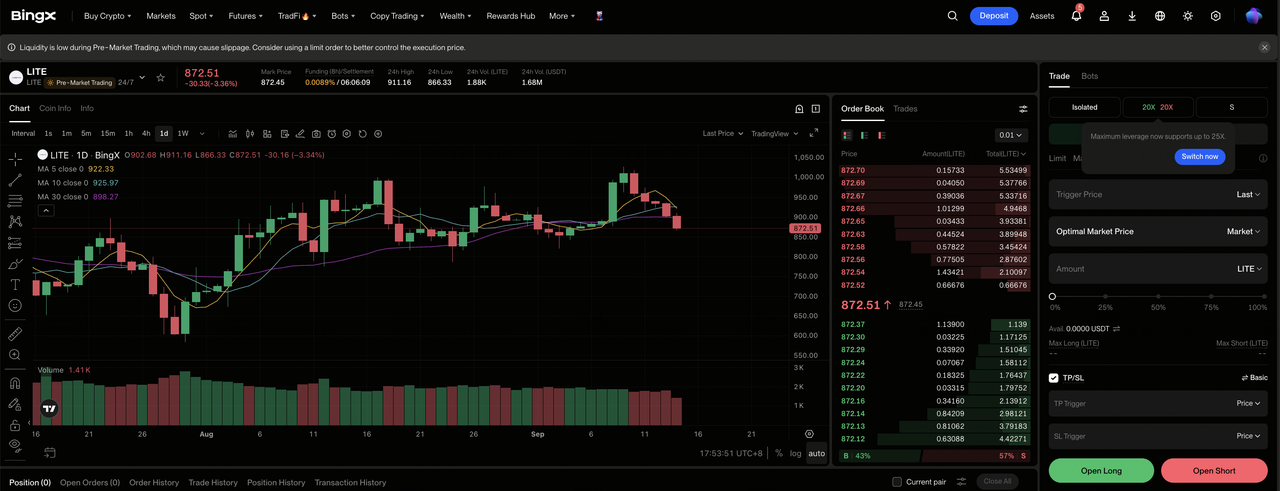
Step 1: Access BingX TradFi. Sign up and navigate to the specialized TradFi section on the BingX exchange dashboard.
Step 2: Select Lumentum (LITE). Search for and select the LITE-USDT perpetual futures contract.
Step 3: Choose your direction. Select Open Long if AI optical shipments and margins continue to exceed expectations. Select Open Short if customer delays or capacity constraints weaken the growth path.
Step 4: Select leverage and margin mode. Choose Isolated or Cross-Margin based on your risk tolerance. The 5.39% September 10 decline shows why conservative leverage and position sizing matter.
Step 5: Execute strict risk protocols. Set Take-Profit and Stop-Loss (TP/SL) levels before or immediately after entering the trade. LITE can react quickly to guidance, customer schedules, product qualifications and AI-capex headlines.
Top 5 Risks to Watch for LITE Investors in 2026
Lumentum's valuation depends on customer demand, manufacturing execution, technology choices and capital structure. These risks can affect revenue, margins and the multiple assigned to the stock.
- Large customer delays could hit revenue quickly: Q4 revenue rose 109.3%, creating a high comparison base. Delays in OCS, module or laser deployments could reduce utilization and pressure the 50.4% non-GAAP gross margin.
- Capacity expansion could hurt margins if yields slip: NVIDIA committed $2 billion as Lumentum expands U.S. production. Qualification delays, material shortages or weak yields could push shipments out while costs arrive earlier.
- Customers may choose different optical technologies: Lumentum is developing ELS, NPO and CPO products alongside 1.6T modules. A shift toward competing architectures or internal silicon-photonics solutions could delay or reduce expected revenue.
- The 153.86% YTD rally raises expectations: At $935.70, the stock already reflects substantial future growth. Shares could fall even with rising revenue if estimates stop increasing or valuation multiples contract.
- Financing can affect per-share returns: Q4 included a $7.8 billion non-cash debt-extinguishment loss, while cash investments fell $433.9 million sequentially. Dilution, debt and weaker cash conversion could reduce the benefit of operating growth.
Final Thoughts: Should You Invest in LITE in 2026?
Lumentum now has operating proof behind its AI optical thesis. Revenue of $1.006 billion, 50.4% non-GAAP gross margin, $3.23 adjusted EPS and a $1.25 billion next-quarter midpoint show that cloud modules, lasers and optical switching are scaling together. NVIDIA's $2 billion commitment adds strategic validation and capacity support.
The tradeoff is a demanding valuation after a 153.86% YTD gain. A conservative investor should watch whether revenue reaches the $1.225 billion to $1.275 billion guide, operating margin approaches 40% and new capacity maintains yields. Those signals would support the $950 to $1,100 Base Case; guidance cuts or margin reversal would strengthen the $700 Bear Case.
Risk Reminder: Stock-linked perpetual futures involve leverage, volatility and liquidation risk. Analyst targets and editorial scenarios are reference points rather than guarantees. Confirm contract availability, use conservative position sizing and set risk controls before trading.
Related Reading
- Top AI Networking Stocks 2026: AI Fabric, Switches, Copper, Fiber, and Optics Connectivity
- Top AI Data Center Stocks to Buy in 2026: Cloud, Servers, and AI Compute Infrastructure
- Top AI Optical Stocks to Buy in 2026: Photonics, Optics, Fiber, and Data Center Interconnects
- Corning (GLW) Stock Forecast 2026: Can AI Optical Growth Push GLW Toward $220?
- NVIDIA (NVDA) Price Prediction 2026: Can AI Infrastructure Growth Drive NVDA Toward $420?
- Coherent (COHR) Price Prediction 2026: Can AI Optics Demand Push COHR Toward $500?
